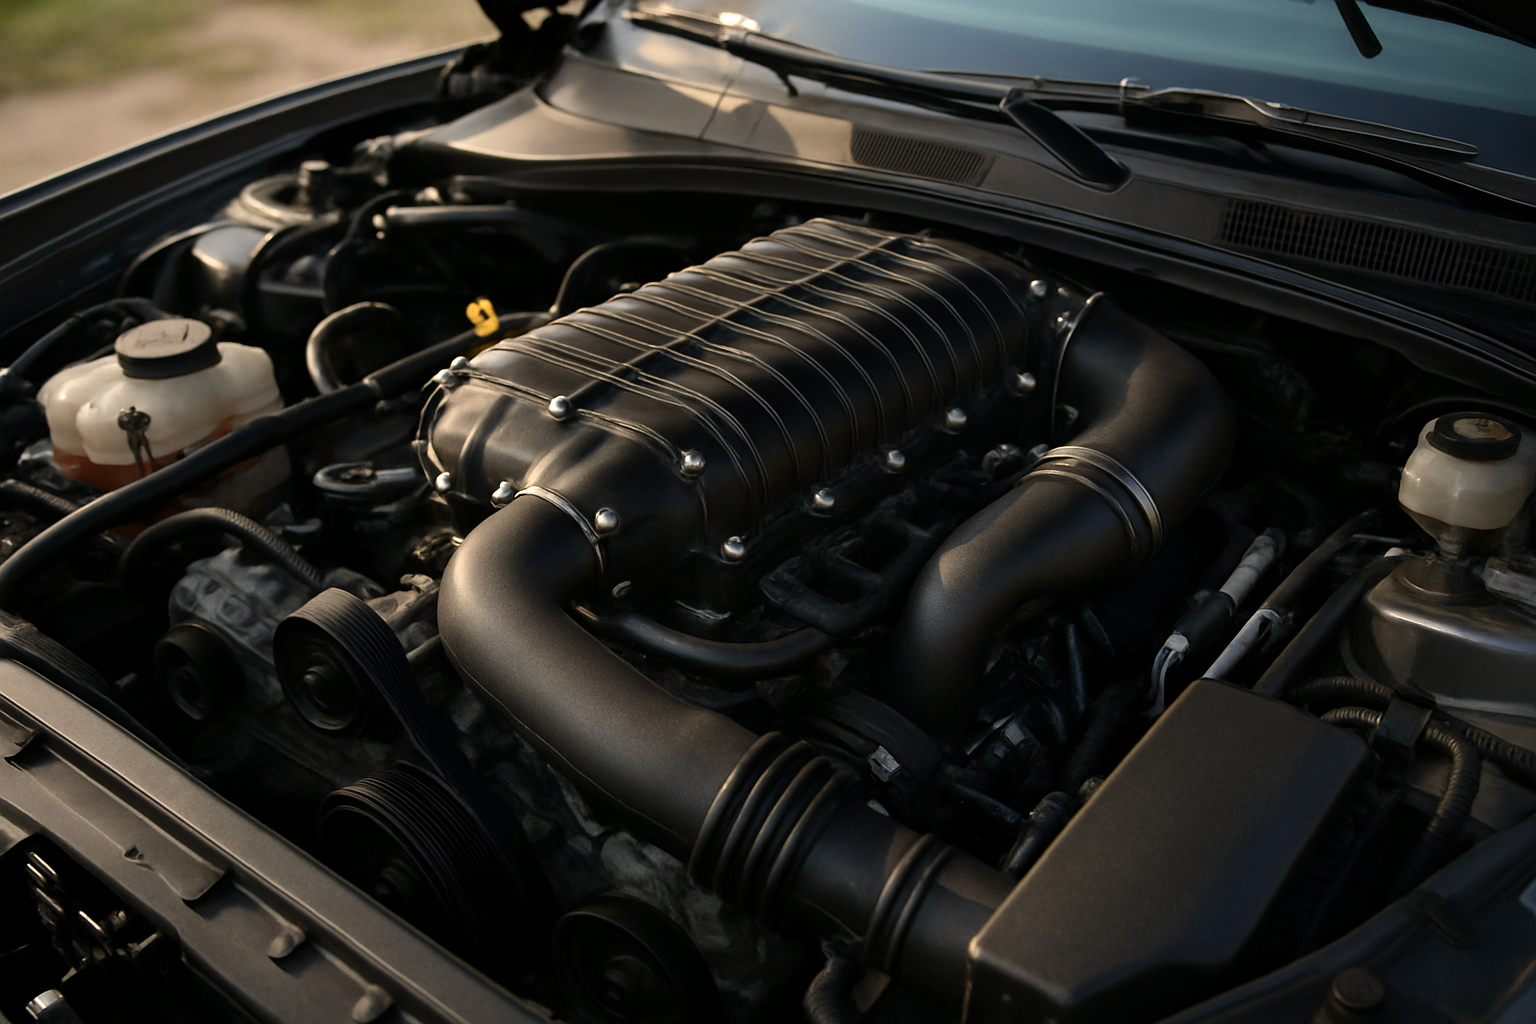
If your vehicle has a factory installed supercharger, the important question is not whether the part sounds expensive to repair. It is whether the issued vehicle service contract actually names the component, what exclusions apply, and what proof is needed if you file a claim.
A factory installed supercharger is part of a vehicle’s performance hardware, but original equipment status does not automatically tell you how a contract will treat it. Coverage depends on the agreement you receive, and the details can change from one plan to another.
How to think about coverage for this part
When shoppers ask about factory installed supercharger coverage, they are usually trying to answer a practical question: if the supercharger needs repair, who pays, and under what conditions? The safest way to compare options is to read the covered components list, then check the exclusions and claim steps.
That matters because a plan name alone can be misleading. Two vehicle protection contracts may sound similar, yet one may include only select engine-related parts while another may organize broader mechanical protection differently. The written contract controls the actual benefit.
What to verify in the contract
Before you request pricing or enroll, look for the exact wording about the supercharger itself, related engine parts, and any performance-related limitations. Also review the deductible, waiting period, mileage rules, pre-existing condition language, and maintenance requirements, because each one can affect a future claim.
If you are comparing plan structure rather than a single component, coverage plans can help you review plan levels, covered components, and the way different contracts organize repair benefits. That comparison is useful when you want to see how coverage comparison, plan levels, and covered components are described before you decide whether to move forward.
Why exclusions matter as much as coverage
Exclusions can be just as important as the covered parts list. A contract may exclude damage tied to modification, lack of maintenance, overheating, abnormal wear, or other conditions that affect a performance component. If the exclusion section is broad, a repair that seems obvious on the surface may still fall outside the agreement.
For drivers who want to understand how broader mechanical protection is organized, powertrain coverage can help you compare engine, transmission, and drivetrain repair coverage. That page is useful when you are sorting through engine transmission drivetrain repair coverage terms and want to see how those systems are described in a written contract.
Coverage decisions also depend on how a claim is presented. If the shop diagnoses a problem, the provider may still require prior authorization before repairs begin. Without that approval, reimbursement can become harder to evaluate even if the repair might otherwise fit the contract.
When a claim is more likely to be reviewed favorably
A claim is generally easier to review when the contract clearly identifies the affected part, the vehicle was maintained according to the agreement, and the repair is not tied to a listed exclusion. If the issue involves an original factory component, that can help with identification, but it still does not override the contract language.
Documenting the issue early can also help. Save the repair order, diagnosis notes, invoices, and any authorization reference number. Those records make it easier to show what happened, when it happened, and which part of the vehicle was involved.
What a comparison should include
When you compare vehicle service contracts, focus on the questions that affect real-world eligibility rather than marketing language. A useful comparison should show:
- which components are listed as covered,
- what exclusions apply to performance or wear-related failures,
- how deductibles and waiting periods work,
- whether prior authorization is required, and
- what documentation is needed for a claim or reimbursement review.
Those details help you separate a broad-sounding plan from a contract that is actually aligned with your vehicle and driving habits. They also make it easier to decide whether the protection is worth requesting a quote for in the first place.
When to request a quote
If you are buying a vehicle with a factory installed supercharger, or you already own one and want to compare protection options, requesting a quote is the simplest next step. A quote can help you review available plan levels and see how the contract language may be written for your vehicle category.
That process is especially helpful if you want to compare core mechanical protection against broader coverage. Some shoppers begin with plan comparisons, then narrow their search after they see which contract terms matter most to them. If you need pricing, you can get a Titan quote and review options in the context of your vehicle, budget, and the parts you care about most.
Bottom line
Factory installed supercharger repairs may be covered under some vehicle service contracts, but coverage is never automatic. The only reliable answer comes from the issued contract, not the part’s factory status or the plan name. Check the covered components, exclusions, deductible, waiting period, and authorization rules before you buy.
If you are comparing protection now, ask for the contract terms in writing and read the component list carefully. Then decide whether the plan matches the way you want to protect your vehicle, and request pricing only after you understand what is and is not included.
Get a Titan quote